Summary
Business Challenge
The deal team reviewed large data rooms on tight committee timelines, and the credit side tracked borrower payments by hand.
- Messy data rooms. Documents were missing, outdated, duplicated, or inconsistent across financial statements, tax records, bank data, loan files, and management spreadsheets.
- Late questions. Issues with revenue quality, EBITDA add-backs, related-party transactions, tax exposure, customer concentration, and debt obligations often surfaced after significant analyst time had already been spent.
- Loan payments checked by hand. Payments were matched against schedules and bank statements line by line, so a short pay or a missing quarterly report could surface well after the fact.
- Every flag had to be traceable. The fund needed one workflow with a clear audit trail from each flag back to its source.
What We Did
1
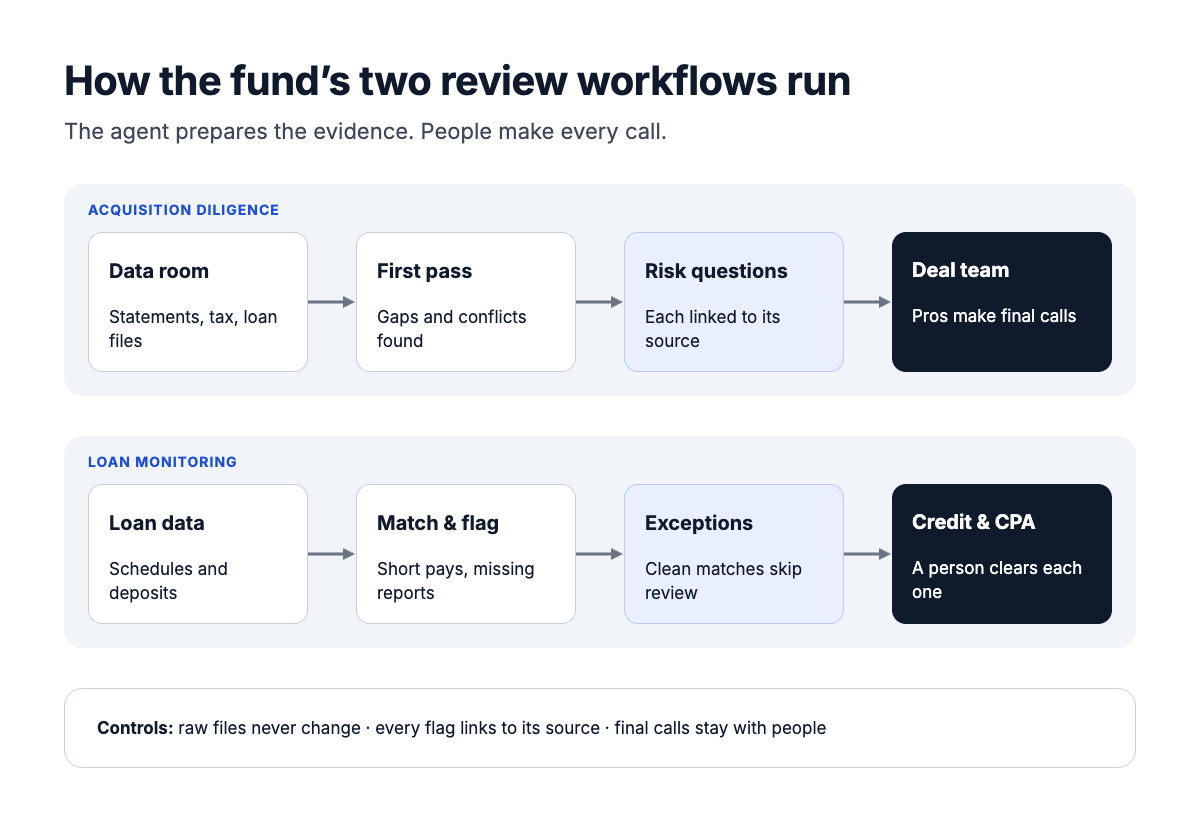
Acquisition Diligence Workflow
For each new deal, the agent runs a first-pass review of the full data room:
•Indexes every file, from audited statements to one-off management spreadsheets
•Checks for missing documents, outdated versions, duplicates, and conflicting figures across sources
•Extracts evidence on revenue, EBITDA, working capital, debt, and tax exposure
•Links every extracted figure and flagged item to its source document and page
•Organizes open diligence questions by risk area
2
Private-Credit Monitoring Workflow
As loan files and bank data arrive, the system continuously:
•Builds expected-payment records by borrower and due date
•Matches them against actual deposits
•Flags short or late pays, missing reports, and unusual transfers
•Routes each exception to the right reviewer
How it works in practice: a short quarterly payment is flagged with the loan terms and bank line attached and sent to the credit reviewer that week.
3
Scope and Controls
•Raw files stay unchanged; agent outputs are versioned separately
•Every extracted figure and flag links back to the underlying document
•Assumptions and unresolved questions are labeled, not presented as findings
•Final tax, legal, accounting, credit, and investment conclusions stay with qualified professionals
Project Results
What changed since launch: